DSCR Loans in Amarillo, TX for Rental Investors
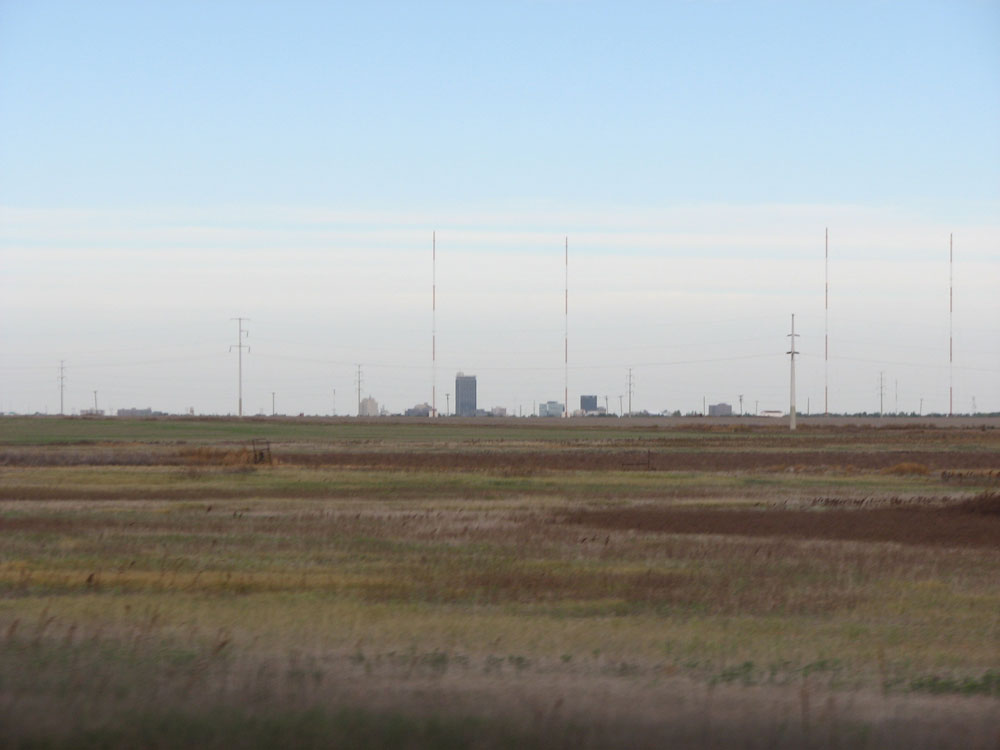
Plan an Amarillo or Canyon rental around supported rent, realistic ownership costs and the right business-purpose financing.
Review your Amarillo investment with Lyndi
Amarillo DSCR loans: start with the rental business
A DSCR loan evaluates rental income against the property’s required debt payment under the selected lender’s rules. It may suit an investor whose personal tax returns do not describe the investment well, but it still requires a complete property and borrower review. Credit, available funds, reserves, appraisal, ownership structure and supported rent matter. The acronym does not mean that a property can finance itself without a down payment or documentation.
For an Amarillo investor, the first question is practical: what rental business will operate at this address? A year-long lease, a furnished monthly tenancy and a short-stay accommodation have different expense patterns and income evidence. Decide on the intended use before comparing programs. The financing should support the actual plan, including vacancies and repairs, rather than a best-case rent number selected to make the ratio work. Read our DSCR financing explanation and review the property with Lyndi.
Amarillo and Canyon need separate rental comparisons
The Census metro population estimate reported through FRED is 276,235 for July 2025. That is a metropolitan figure, not the population of the city of Amarillo or a forecast of tenants available for a particular home. Metro size provides useful context for this guide, while the financing decision remains tied to the subject property and supported income.
West Texas A&M University’s main campus is in Canyon, approximately 20 miles south of Amarillo according to the university. An investor evaluating student-oriented rentals should therefore compare actual Canyon locations and commuting arrangements rather than assume that every Amarillo address serves the same tenant pool. Check drive times at relevant hours, lease lengths, parking, occupancy limitations and who pays utilities. A listing described as near a university still needs a defensible set of competing rentals.
For an Amarillo home, organize comparable leases by location, bedroom count, condition and rental term. Do not blend a renovated furnished listing with an older unfurnished annual rental without accounting for the difference. An advertised asking rent is a lead for research, not proof that the property will produce that income. Obtain signed lease information where available and let the lender determine what documentation supports underwriting.
Build the payment estimate before negotiating the purchase
Begin with the proposed loan amount, then estimate principal and interest using an actual program discussion. Add property taxes, an insurance quote for the intended rental use, and association dues if applicable. Confirm whether the lender includes other recurring charges in the DSCR denominator. A quote that leaves taxes or insurance out can make a marginal property appear comfortable.
For a Panhandle acquisition, ask an insurer about wind and hail coverage, deductibles, roof age and any exclusions that apply to this property. The answer should come from an address-specific quote. A seller’s current premium may reflect a different policy, occupancy or deductible. If a repair is needed before coverage can bind, include its cost and timing in the acquisition plan rather than treat it as a problem for after closing.
The seller’s tax bill is also a starting reference. Confirm the assessment, applicable exemptions and how the property will be taxed under your ownership and rental use. A principal-residence exemption attached to a seller’s circumstances should not silently carry into an investor forecast. A realistic estimate makes both the lender conversation and your negotiation more useful.
Illustrative purchase: separate DSCR from net cash flow
Consider a hypothetical Amarillo rental with supported monthly rent of $1,700 and a monthly loan payment including taxes and insurance of $1,360. Dividing $1,700 by $1,360 produces a 1.25 DSCR. These figures demonstrate the arithmetic; they are not a local rent estimate, interest-rate quote or assurance of eligibility. The applicable program may use a different method or require a different ratio.
Now reserve $85 monthly for vacancy, $136 for management, $100 for routine maintenance and $100 for capital replacements. Those illustrative costs total $421, while rent less the debt payment is only $340. The result is an $81 monthly shortfall before any additional costs. A qualifying-looking ratio therefore cannot substitute for an operating budget. Your actual allowances should reflect the property, lease and service quotes.
Stress the same scenario with rent of $1,600 and a payment of $1,420. The ratio falls to approximately 1.13 and the margin before operating expenses falls to $180. Compare this outcome with your reserves and willingness to hold through a vacancy. Use our DSCR calculator for the ratio, then separately calculate the ownership cash flow. Confirm program calculations with the loan team.
Cash to close and cash to keep
If a hypothetical purchase price is $220,000 and a program requires a 25% down payment, the down payment alone is $55,000. Closing costs, prepaid items, initial repairs and lender-required reserves come on top of that amount. This is an illustration rather than a statement that every DSCR program uses 25%. Discuss the loan-to-value options before treating the down payment as settled.
Maintain an operating cushion after closing. A roof deductible, appliance failure and month without rent can arrive close together. Using nearly all available cash to buy a property may leave an investor dependent on expensive short-term borrowing for ordinary ownership expenses. Map the cash needed from contract through rent-ready condition and the first several months of operation.
Document the source and availability of funds early. Transfers between business and personal accounts, entity ownership, sale proceeds and gifts can require different evidence depending on the lender. Clear records make it easier to determine what is usable and what must be resolved before closing. Review our DSCR requirements guide alongside the specific program checklist.
Condition and repairs: make rent-ready timing explicit
Walk the property with a repair list and a timeline. Roof condition, plumbing, electrical systems, heating and cooling, and deferred maintenance can affect expenses, insurance and the lender’s assessment. Cosmetic appeal alone does not establish that the home can be occupied or insured on the proposed closing schedule. Obtain inspections and trade estimates suited to the issues present.
Distinguish a stabilized rental purchase from a substantial rehabilitation. A standard DSCR program should not be assumed to fund every distressed property or reimburse repairs. Ask whether the current condition is acceptable, which work must happen before closing, and whether another financing approach is needed. Do not base projected rent on a renovated condition without budgeting and documenting how the property will reach it.
For a currently occupied home, review the lease, payment history, deposits and any unresolved maintenance requests. Confirm the practical transition of ownership and management. If the lease rent is below your projection, identify when and how a lawful change could occur. A higher future rent should not be presented as income already received.
Annual leases, furnished rentals and short stays
An annual rental generally needs a different operating budget from a furnished short-stay property. Furniture replacement, utilities, internet, cleaning, booking fees and guest turnover can materially reduce the apparent premium in gross revenue. Separate each cost instead of using one vague management percentage. Ask the lender which income sources and rental arrangements the program accepts.
The City of Amarillo’s lodging-tax page describes monthly hotel occupancy tax filing and annual hotel occupancy tax registration for lodging providers. That tax process is a separate issue from approval to use a particular address for short stays. Verify current tax obligations, zoning, association restrictions, insurance and lender acceptance for the proposed use. Do not apply Amarillo guidance automatically to a Canyon address.
If the short-stay plan is uncertain, model an annual-lease fallback with supported local comparisons. Does the property still fit your budget after the furnishings and higher initial costs? An investor should understand the cost of changing strategy before buying. Our short-term rental financing guide explains additional review questions; it does not establish local permission.
Refinance an Amarillo rental with the same discipline
A refinance should improve a defined investment objective. Compare the existing payment with the proposed payment, cash required at closing, remaining term, closing costs and any prepayment penalty. A lower advertised rate may not deliver the result you expect if the loan amount grows, costs are financed or the term changes. Review the full transaction rather than one number.
For illustration, $1,900 of supported rent divided by a $1,520 monthly payment produces a 1.25 ratio. If a cash-out transaction increases the payment to $1,700, the ratio becomes approximately 1.12 and the margin before operating costs shrinks by $180 a month. The new cash may have a useful purpose, but that purpose should justify the ongoing effect on the rental.
Document how you will use cash-out proceeds and preserve reserves for the subject property. Funding a second purchase with every dollar can compound vacancy and repair risks across two homes. Confirm value, seasoning, ownership and rental-income documentation before assuming a particular cash-out amount is available.
LLC ownership and genuine business-purpose financing
An LLC can organize ownership, but it does not automatically establish loan eligibility or change how a property will actually be used. Eligible entity borrowers may need formation documents, evidence of authority to sign, ownership information and guarantees under the program. Coordinate the intended vesting with the lender, title provider and your own advisers before closing.
This guide concerns genuinely non-owner-occupied business-purpose investment financing. A home used as a personal residence requires a different loan and licensing review. Texas residential mortgage statutes define their scope with reference to loan purpose; using a DSCR label or an LLC is not a substitute for checking the transaction. Mixed personal use should be disclosed at the beginning. Read our LLC financing guide for ownership questions, then confirm the actual facts.
Send a scenario that can be reviewed
Provide the full property address, asking price or estimated value, desired loan amount, rental term, actual lease or rent evidence, estimated taxes, insurance, association dues, repair needs and current occupancy. Include the ownership structure, available closing funds and intended use. This lets the team identify missing information before you depend on a financing assumption in a contract.
Keep a separate operating worksheet with vacancy, management, maintenance, capital reserves and utilities paid by the owner. Our broader Texas DSCR hub connects other metro guides. Investors comparing Panhandle opportunities can also review Lubbock DSCR financing. For practical rental budgeting, explore Blue Castle Management’s leasing resources alongside local service quotes.
A useful next step is a property-specific discussion, not a promise based on the city name. Lyndi can review the scenario, explain the documentation path and compare available programs for an eligible investment. Send the numbers you have and identify what is still estimated so the review starts with a transparent picture.
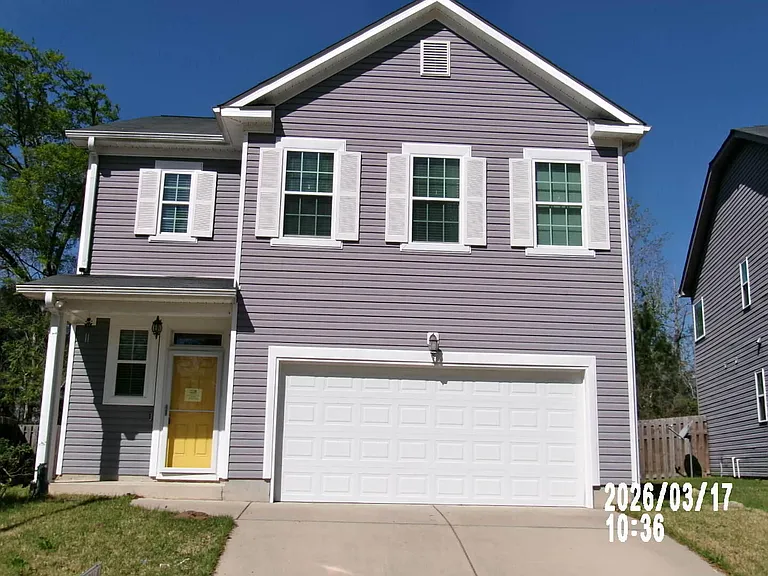
Real closing example — Georgia
No Personal Income Needed for This Rental Purchase
This example is from Grovetown, Georgia, not Amarillo. See how an investor used the property’s estimated $1,826 monthly rent to qualify for an $184,000 DSCR loan at 7.49% with no prepayment penalty—and how the deal pencils to approximately $205.83 monthly cash flow before other operating expenses.
DSCR and Investor Loan Guidance
Talk Through DSCR Loan Options With Lyndi Gajan
Real estate investors can work with Lyndi Gajan to talk through DSCR loan questions, rental income scenarios, refinance options, and investor documentation before choosing a loan path.
Lyndi Gajan NMLS ID 88249. 360 Mortgage Inc. NMLS ID 80777. Loan availability, licensing, and guidelines vary by state, property, and loan purpose.
Request your Amarillo investor financing review
Share the address and investment plan so Lyndi can review the property, supported rent and available program options.
Frequently asked questions about Amarillo DSCR loans
Can an Amarillo DSCR loan finance a home I will occupy?
This guide concerns non-owner-occupied business-purpose rentals. A personal residence or mixed personal-use plan needs a separate financing and licensing review.
Is Canyon the same rental market as Amarillo?
No. Compare the actual property location, lease term, condition and tenant use. West Texas A&M’s main campus is in Canyon, so a university-oriented rental needs location-specific research.
Does a 1.25 ratio guarantee positive rental cash flow?
No. Vacancy, management, maintenance, capital reserves and owner-paid utilities may sit outside the lender’s ratio. Budget those costs separately.
Can an LLC borrow under a DSCR program?
Some programs accept eligible LLC borrowers, subject to entity documentation, signing authority, guarantees and other underwriting requirements. An LLC alone does not establish a licensing exemption.
Does lodging-tax registration approve short stays at an Amarillo address?
No. Verify tax obligations separately from zoning, association rules, insurance and lender acceptance for the proposed address and rental use.
What information helps start an Amarillo DSCR review?
Provide the address, purchase price or value, loan request, rent evidence, taxes, insurance, association dues, repairs, occupancy, closing funds and ownership structure.
Sources and review notes
Local facts checked October 8, 2026. All financing and expense examples are hypothetical, not market rent estimates or advertised loan terms.