Explore Longview rental financing with property income, local inspection and short-stay requirements, and a realistic ownership budget.
Review your Longview investment with Lyndi
A Longview rental needs an address-specific financing plan
Longview investors can use an eligible debt service coverage ratio program to evaluate financing primarily through a rental property’s supported income. The useful starting point is the proposed address, lease structure and complete payment, rather than an assumed citywide rent. A house near the LeTourneau campus, an older downtown property and a three-unit building can present different operating and documentation questions even when their asking prices are similar.
This guide addresses genuinely non-owner-occupied, business-purpose rental financing. Disclose any plan for personal occupancy or mixed personal use before reviewing a program. Credit, available funds, reserves, appraisal, condition and the lender’s requirements still matter. A DSCR calculation helps organize the financing discussion; it does not establish that a particular property or borrower will qualify.
Use the metro population without confusing it with the city
The U.S. Census Bureau’s July 1, 2025 estimate places the Longview metropolitan area at 297,315 residents. The figure describes the metro, not the population inside Longview’s municipal boundary. That makes Longview eligible for this metro guide, but population alone does not establish tenant demand, achievable rent or the quality of an investment. Treat it as geographic context and build the investment decision from evidence tied to the subject property.
Start a comparison file with actual competing rentals, their bedroom counts, condition, lease duration, included utilities and marketing dates. Keep Longview and nearby communities distinct where school assignments, services or tenant destinations differ. Do not import Tyler rents into a Longview analysis simply because both markets are in East Texas. A nearby market can provide perspective without becoming an interchangeable rental comparison.
LeTourneau access is useful context, not a rent guarantee
LeTourneau University lists its main campus at 2100 South Mobberly Avenue in Longview. The university’s travel information also identifies access from Interstate 20 using Estes Parkway. For a property marketed toward people associated with the campus, check the specific route, parking and daily destination. A listing described as being near the university can still involve a different practical commute from another home with similar mileage.
Before building a student-oriented rental budget, decide whether the intended arrangement is an ordinary whole-house lease or separate room leases. Ask the lender which arrangement it accepts and how rent would be supported. Review occupancy, parking and any applicable local requirements for the actual plan. Campus proximity is a location fact, not proof of off-campus demand or an assurance that student tenants will fill the property. Underwrite a fallback tenant strategy instead of relying on one audience.
Downtown character and Interstate 20 access need separate comparisons
A historic downtown property may offer a setting that a prospective tenant values, but age and character also require a careful condition review. Inspect the roof, electrical service, plumbing, heating and cooling, drainage and any previous alterations. Obtain quotes for the work needed to deliver the home in rentable condition. Avoid treating cosmetic updates as evidence that concealed systems are ready for long-term ownership.
For an investment promoted around Interstate 20 access, evaluate the actual driveway-to-destination route and the features tenants would use every day. Road noise, parking, outdoor space and the layout can affect the property’s appeal independently of regional access. Document those differences when selecting comparable rentals. This is an underwriting approach, not a claim that one Longview neighborhood produces higher returns than another. Let property evidence support the conclusion.
A three-unit property triggers a local inspection question
Longview’s Code Compliance Division states that its multifamily permitting and inspection program includes rental properties with three or more units. A triplex therefore deserves an early local compliance check alongside the financing review. Ask the city about the subject property’s status, required inspections and unresolved conditions before assuming that advertised units are ready to rent.
Keep that operating requirement separate from the lender’s property classification. A program’s willingness to finance a three- or four-unit rental does not settle local permitting. Verify the legal number of units, utility arrangements, existing leases and any work that changed the building. Request records from the seller and obtain appropriate inspections. For larger properties, review a separate commercial financing path rather than extending a one-to-four-unit assumption. Our multifamily DSCR guide explains additional questions to organize.
Calculate coverage using the lender’s complete payment method
For a residential DSCR program, ask exactly which supported income figure and payment components the lender uses. A common approach compares monthly qualifying rent with principal, interest, property taxes, insurance and applicable association charges. Program methods differ. An investment spreadsheet that omits insurance or dues can look stronger than the actual underwriting result, so reconcile every component before relying on a ratio.
Consider a hypothetical Longview rental with $2,000 of supported monthly rent and a $1,600 qualifying payment. The ratio is 1.25: $2,000 divided by $1,600. Those figures are an illustration, not a Longview market-rent estimate, loan quote or approval threshold. The $400 difference is not net profit. Vacancy, management, maintenance and future replacements still need to be funded. Review our rental-income qualification guide for the distinction between a rent assumption and lender-accepted evidence.
Stress-test vacancy and costs before deciding on a purchase
Using the same hypothetical example, $2,000 monthly rent produces $24,000 of scheduled annual revenue. One vacant month reduces collected revenue to $22,000, while twelve $1,600 payments total $19,200. That leaves $2,800 before other operating costs. An illustrative management allowance of 8% of collected rent is $1,760, leaving $1,040 before repairs, leasing expenses and capital replacements. Even an apparently comfortable ratio can leave a narrow ownership margin.
If insurance and taxes increase the qualifying payment by $150 per month, the ratio falls to approximately 1.14 and annual payments increase by $1,800. Hold purchase price, loan structure and reserve assumptions open until you have property-specific quotes. A larger down payment might improve payment coverage but reduce cash available for repairs. Compare both effects rather than optimizing the ratio alone. Read our down-payment guide and reserve guide as you organize the decision.
Check Longview drainage and flood exposure before locking the budget
The City of Longview publishes flood-prone-area and FEMA flood-hazard mapping resources through its Floodplain Administrator. Its page also describes review of construction in and near floodplains. Use those resources to investigate an address and planned repairs; a general map does not replace a property-specific determination or establish that a home has never flooded.
Ask about site drainage, prior water intrusion, relevant permits and the insurance implications of the proposed rental use. Obtain written insurance quotes that identify deductibles and coverage limitations. Lender-required flood coverage and a broader owner decision about flood protection are separate questions. Include any required premium in the financing calculation and consider uncovered risks in the ownership budget. An inland East Texas location should not become a reason to skip drainage due diligence.
Longview short-stay operations have a different local process
Longview’s official short-term residential rental page describes a registry and application process under its Unified Development Code. It distinguishes whole-unit short-term rentals from bed-and-breakfast arrangements where the owner or lessee lives on-site. Consult the current application and confirm address-specific requirements with Development Services before purchasing for a furnished short-stay strategy.
An owner-occupied bed-and-breakfast plan falls outside the genuinely non-owner-occupied scope of this guide. For an eligible whole-unit investment, lender acceptance, local authorization, insurance and any association restrictions still require separate confirmation. Build an annual operating forecast using defensible booked nights and include cleaning, utilities, management, platform costs, furnishings and replacement reserves. Do not substitute a peak nightly rate for supported annual income. Our short-term rental financing guide provides a broader documentation framework.
Refinance only when the new loan serves a clear purpose
A Longview rental refinance might change payment structure, replace an existing loan or release equity for another investment. Compare the current loan with the complete proposed transaction, including closing costs, remaining term and any prepayment penalty. Cash received at closing is useful only when the obligations left on the subject rental remain manageable.
For illustration, $2,000 of supported rent against a $1,600 payment gives a 1.25 ratio. Increasing the payment to $1,850 through a cash-out transaction reduces it to approximately 1.08. That change removes $250 of monthly margin before other operating expenses. Confirm value, seasoning, ownership history, condition and rental documentation before treating a cash-out amount as available capital. Preserve reserves for the Longview property rather than committing all proceeds to the next acquisition.
Bring a complete Longview file to the first review
Send the full property address, contract price or estimated value, requested loan amount, supported rent, lease duration, occupancy, taxes, insurance, association charges, repairs and available funds. For an occupied property, include the lease and explain any arrears or concessions. For a vacant property, separate documented comparable evidence from the rent you hope to achieve. For a multi-unit purchase, identify each unit and utility responsibility.
If an LLC will own the property, organize formation records, ownership details and signing authority. An LLC alone does not establish a licensing exemption or convert personal occupancy into a business-purpose loan. Texas Finance Code Chapter 156 incorporates the consumer-purpose definition in Chapter 180; the state’s mortgage regulator also describes rental acquisition as business or investment purpose in its specific FAQ scenario. Actual purpose and use control the review. Compare our Texas DSCR hub and Tyler guide, and use Blue Castle Management’s leasing resources to plan operations alongside local quotes.
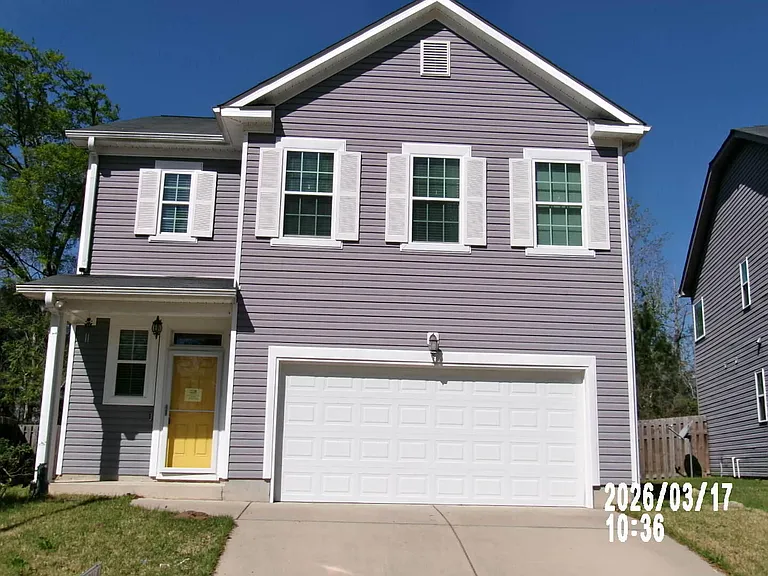
Real closing example — Georgia
No Personal Income Needed for This Rental Purchase
This example is from Grovetown, Georgia, not Longview. See how an investor used the property’s estimated $1,826 monthly rent to qualify for an $184,000 DSCR loan at 7.49% with no prepayment penalty—and how the deal pencils to approximately $205.83 monthly cash flow before other operating expenses.
DSCR and Investor Loan Guidance
Talk Through DSCR Loan Options With Lyndi Gajan
Real estate investors can work with Lyndi Gajan to talk through DSCR loan questions, rental income scenarios, refinance options, and investor documentation before choosing a loan path.
Lyndi Gajan NMLS ID 88249. 360 Mortgage Inc. NMLS ID 80777. Loan availability, licensing, and guidelines vary by state, property, and loan purpose.
Request your Longview investment financing review
Share the address and rental plan to review eligible options.
Frequently asked questions about Longview DSCR loans
Can a Longview investment qualify using rental income?
An eligible DSCR program may use supported property rent. Credit, assets, reserves, appraisal, condition and the actual rental arrangement still require review.
Is the 297,315 population estimate for Longview city?
No. The Census estimate is for the Longview metropolitan area as of July 1, 2025, not the city boundary.
Does Longview inspect triplex rental properties?
The city states that its multifamily permitting and inspection program includes rental properties with three or more units. Confirm the subject property’s requirements with Code Compliance.
Does being near LeTourneau guarantee student rental income?
No. Campus access is location context. Verify comparable rentals, the proposed lease arrangement and lender-accepted income evidence.
Can I use this guide for an owner-occupied bed and breakfast?
No. This guide addresses genuinely non-owner-occupied business-purpose investment financing. Disclose personal occupancy and seek a separate review.
Does an LLC automatically establish a mortgage licensing exemption?
No. The actual purpose and occupancy matter. Entity formation alone does not establish exemption or loan eligibility.
Sources and review notes
Facts reviewed October 13, 2026. Financing and operating examples are hypothetical, not local transactions, rent estimates or advertised loan terms.