DSCR Loans in El Paso, TX
Evaluate supported rent, property costs and a genuine business-purpose financing plan.
Review your rental investment with Lyndi
El Paso rental financing starts with the address and the lease
An El Paso investment can work differently from a conventional home purchase. An eligible debt service coverage ratio program may use supported rental income to evaluate repayment capacity rather than a standard personal-income calculation. The property, borrower, funds, condition and loan purpose still matter. DSCR financing is an option to review, not automatic approval based on a rent estimate.
Before requesting terms, decide whether the property will be an annual rental, a furnished tenancy or a short-stay operation. Identify existing occupants, needed repairs and any intended personal use. This guide concerns genuinely non-owner-occupied business-purpose investment financing. Read our explanation of how DSCR loans work, then submit the actual property facts for review.
A large border metro is not a single rental market
The 2024 American Community Survey profile reports 877,840 residents in the El Paso metropolitan area. That regional figure clears our metro-size criterion; it is not the city’s population, a rent forecast or a measure of demand for your particular home. Rental comparisons should match the property’s location, layout and condition.
Start a comparison file for the address rather than treating all El Paso listings as interchangeable. Record actual lease terms, parking, included utilities, cooling equipment and access to the tenant’s destination. A higher asking rent elsewhere in the metro may involve a different product. Border-region context should not replace an address-level operating plan.
Fort Bliss access: verify the gate, not just the distance
Fort Bliss publishes official gate information and housing resources. For an investment intended to serve people traveling to the installation, compare the actual route to the relevant entry point and current access requirements. Straight-line distance to the installation boundary may be a poor description of a tenant’s daily trip.
Do not assume military proximity establishes guaranteed occupancy or makes a property eligible for a particular loan. Compare ordinary lease evidence and a fallback tenant audience. Ask a qualified property manager about lease administration appropriate to the actual tenancy, including any applicable military protections. The lender still needs supported income, an acceptable property and an eligible business-purpose transaction.
Separate supported rent from the investor’s wish list
For an occupied house, provide the lease, payment history, concessions, deposits and renewal date. Explain whether the owner pays any recurring services. A promised increase at the next turnover is different from collected rent under the current agreement. Show both figures separately instead of blending them into one favorable estimate.
For a vacant acquisition, collect similar properties and request the lender’s required appraisal and rent documentation. Identify repairs necessary to achieve the proposed rent and who will complete them. Furnishing costs, new cooling equipment or improved parking belong in the budget. Ask whether the program accepts the home before that work is finished.
An illustrative DSCR calculation and a realistic ownership budget
Suppose supported rent is $1,950 per month and the proposed payment including principal, interest, property taxes and insurance is $1,560. The simple ratio is 1.25. These numbers are hypothetical, not El Paso market rents, a current rate quote or an approval threshold. The lender determines which income and payment components it accepts.
The $390 difference is not necessarily profit. Illustrative monthly allowances of $97.50 for vacancy, $156 for management, $110 for maintenance and $100 for capital replacement total $463.50. The remaining cash flow would be negative $73.50 before other costs. Compare the underwriting ratio with a separate operating budget; the two answer different questions.
If supported rent instead falls to $1,800 while the payment remains $1,560, the simple ratio declines to approximately 1.15. That change also removes $150 from the monthly operating margin. Use our DSCR calculator for a starting calculation, then stress test rent, expenses and vacancy using your own evidence.
Cooling, roof condition and the rent-ready plan
Inspect the actual cooling system, roof, windows, plumbing and electrical service. Obtain professional evaluations where needed rather than assuming a listed feature confirms useful life. Ask how equipment is maintained, which bills the tenant pays and what must be replaced before occupancy. Reliable service and an affordable operating plan matter together.
Keep repairs that improve marketability separate from repairs required for safe occupancy or lender acceptance. Document bids, permits where applicable and the expected completion date. A standard rental loan should not be assumed to fund an unfinished renovation. Resolve condition questions early enough to choose a suitable financing path instead of depending on projected rent from a future finished product.
El Paso flood review still belongs on the checklist
An inland location does not eliminate the need to review flood information. The city’s official flood-zone page links to FEMA resources and an El Paso County viewer, and discusses preliminary map revisions. Check the actual address and distinguish effective maps from preliminary materials. Ask the lender and insurance professional which records govern the transaction.
Inspect drainage, grading and evidence of earlier water entry as part of the property’s condition review. Obtain relevant insurance quotes before finalizing the payment estimate. A map designation and a physical inspection answer different questions; neither should be used to skip the other. Coverage, deductibles and lender requirements depend on the specific property and proposed arrangement.
Down payment is only one part of closing liquidity
A hypothetical $250,000 purchase with a 25% down payment requires $62,500 for that down payment. This is an illustration, not a universal DSCR requirement. Closing charges, prepaid taxes, insurance, initial repairs and reserves add to the funds needed. Ask Lyndi to organize program options around the actual transaction and available cash.
Do not assume the seller’s tax treatment or premium will continue under your ownership. Confirm a rental-appropriate tax estimate, current coverage quotes and any association dues. Review the DSCR documentation checklist and identify funds that must remain available after closing. A reserve shown to the lender should also support the property’s real operating needs.
Annual rentals and furnished tenancies need different evidence
An annual lease may have fewer turnovers, while a furnished tenancy can introduce furniture replacement, utilities and additional service obligations. Compare the net result rather than advertised gross income alone. Establish the proposed rental duration and ask which documentation the lender uses for that arrangement.
If the investment depends on shorter bookings, verify current city or county requirements, zoning, association restrictions and the insurer’s acceptance directly for the address. Do not infer permission from an active online listing. Our short-term rental financing guide helps organize loan questions, while local authorities determine applicable use requirements.
Prepare an annual-lease fallback with relevant comparisons. Keep the proposed debt payment unchanged and rerun expenses for that alternative. Could you carry the property through repairs, marketing and a vacancy if the preferred plan cannot start on schedule? The exercise identifies the cash needed; it does not guarantee another tenant or an approved alternative use.
Refinancing should improve a defined business objective
A rate-and-term refinance or cash-out request should be evaluated against the existing obligation and intended use of the funds. Compare the new payment, closing costs, term and any prepayment provisions. Lowering one payment component does not necessarily lower the full cost of ownership, especially if the repayment period changes.
For illustration, rent of $2,100 with a $1,680 payment yields 1.25. A cash-out payment of $1,850 lowers the ratio to about 1.14 and reduces the pre-expense monthly margin by $170. Use that comparison alongside the value of the proposed project. Keep a reserve for the El Paso rental instead of allocating all proceeds elsewhere.
Business purpose and ownership must match the facts
Texas mortgage statutes define the regulated residential mortgage loan by its primarily personal, family or household purpose, and the regulator’s guidance distinguishes genuine rental acquisitions from personal residences. This page is limited to business-purpose investment scenarios; it does not claim eligibility for owner-occupied or disguised personal-purpose borrowing.
Some lenders accept eligible LLC borrowers with entity records, ownership details, signing authority and guarantees. An LLC alone does not establish a licensing exemption or change actual occupancy. Review our LLC borrower guide and describe the real use of the home before choosing a program.
Turnover timing can change the annual result
Translate monthly projections into a twelve-month schedule. If an El Paso lease ends before planned repairs, identify when contractors can start, how long inspections may take and when the home can realistically be shown. A month with no tenant still carries debt service and ownership expenses. Avoid treating a deposit or borrowed reserve as recurring rent.
For illustration, eleven collected months at $1,950 produce $21,450 in annual receipts. Twelve payments of $1,560 total $18,720, leaving $2,730 before operations. That is an average pre-expense margin of $227.50 per month, substantially below the $390 shown by a fully occupied monthly example. The annual comparison is an investor stress test, not a substitute for the lender’s DSCR formula.
Ask how rent collection, notices, emergency maintenance and inspections will be handled if you live elsewhere. Obtain a written management proposal and distinguish leasing charges from recurring management fees. Include travel or local service costs that your plan genuinely requires. The goal is to know who will keep the property operating and what that service costs before relying on the projected surplus.
Prepare a useful El Paso investment package
Send the full address, price or estimated value, purchase or refinance objective, requested amount, rent evidence, proposed lease duration and current occupancy. Add tax and insurance estimates, dues, condition details, repair bids and funds available for closing and reserves. Identify unanswered questions so they can be resolved before the financing decision.
For broader planning, visit the Texas DSCR hub and compare the separate Lubbock rental financing guide. For an operating checklist, Blue Castle Management’s leasing education can help organize tenant and maintenance questions; it is not a statement of El Paso service availability. A clear property package gives Lyndi a practical basis for discussing eligible loan paths.
Real closing example — Georgia
No Personal Income Needed for This Rental Purchase
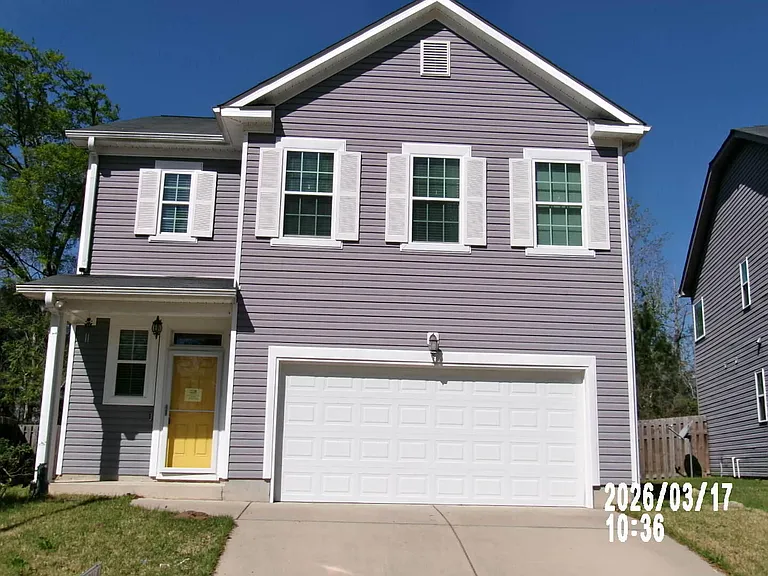
This example is from Grovetown, Georgia, not El Paso. See how an investor used the property’s estimated $1,826 monthly rent to qualify for an $184,000 DSCR loan at 7.49% with no prepayment penalty—and how the deal pencils to approximately $205.83 monthly cash flow before other operating expenses.
DSCR and Investor Loan Guidance
Talk Through DSCR Loan Options With Lyndi Gajan
Real estate investors can work with Lyndi Gajan to talk through DSCR loan questions, rental income scenarios, refinance options, and investor documentation before choosing a loan path.
Lyndi Gajan NMLS ID 88249. 360 Mortgage Inc. NMLS ID 80777. Loan availability, licensing, and guidelines vary by state, property, and loan purpose.
Request your El Paso financing review
Share the address, supported income and rental plan for an eligible investment-program review.
Frequently asked questions about El Paso DSCR loans
Can I use an El Paso DSCR loan for a personal residence?
This guide concerns genuine non-owner-occupied business-purpose investment financing. Disclose actual occupancy and any personal use before a program review.
Does Fort Bliss proximity guarantee rental income?
No. Verify the actual gate route and access requirements, and support rent with relevant lease evidence rather than assuming guaranteed demand.
Should an El Paso investor check flood information?
Yes. Review address-specific effective flood information, relevant preliminary changes, lender requirements and insurance quotes.
Does a 1.25 ratio guarantee positive operating cash flow?
No. Vacancy, management, maintenance, capital replacements and other costs can exceed the margin remaining after debt payment.
Does an LLC automatically make the loan eligible?
No. The actual purpose, occupancy, property and lender requirements govern the review. Entity records and guarantees may also be required.
What should I send Lyndi for an El Paso rental review?
Send the address, transaction objective, value or price, loan amount, rent evidence, lease plan, expenses, repairs, occupancy and available funds.
Sources and review notes
Local facts checked October 8, 2026. Financial examples are hypothetical, not market-rent estimates or quoted loan terms.