360 Mortgage Real Closing Scenario
Addis, LA Refinance Case Study: 668 Credit and High DTI
An Addis homeowner completed a conventional refinance with a 668 credit score and a recorded 50.99% debt-to-income ratio. The closing shows why credit, monthly debt and home equity need to be evaluated together.
Discuss Your Refinance With Lyndi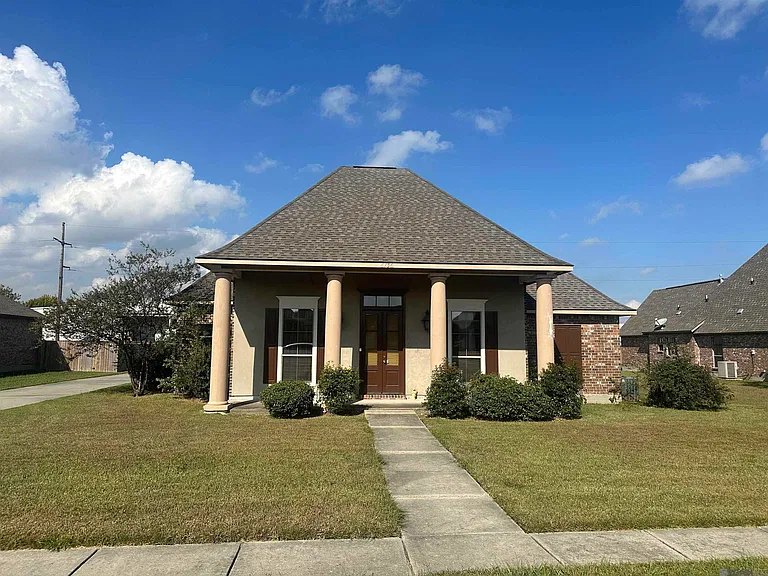
Closed-loan snapshot
A $234,025 conventional refinance of a primary residence in Addis, Louisiana, closed on September 21, 2026. The closing record lists a 668 credit score, 68% loan-to-value ratio and 50.99% debt-to-income ratio.
Loan Snapshot
Conventional refinance
$234,025
668
50.99%
68%
30-year fixed
6.375%
7.185%
September 21, 2026
Historical terms from one closed primary-residence transaction, not a current rate quote. LTV means loan-to-value; DTI means debt-to-income ratio. Rates and APR are reported from the closing record.
The Challenge: High DTI and a Credit Score Below 680
The borrower’s credit score was 668. A score below 680 can affect available loan options and pricing, depending on the program and lender. It does not explain the full credit history or determine the result on its own.
Debt-to-income ratio, or DTI, compares monthly debt payments with gross monthly income before taxes. Lenders use it to assess repayment capacity. A higher ratio leaves less room for additional debt and everyday expenses. Read the CFPB explanation of DTI.
The recorded 50.99% DTI means qualifying monthly obligations represented just over half of qualifying gross monthly income. That made debt and income evaluation a central issue. This is the DTI reported for this closing, not an advertised conventional-loan limit or a promise that another borrower at that ratio will qualify.
The 68% LTV shows substantial equity relative to the recorded loan amount. Equity matters in a refinance, but it does not replace income and credit review. The useful lesson is to look at the entire file rather than assuming that one number determines the answer.
The Result: A Closed 30-Year Conventional Refinance
The loan closed on September 21, 2026, with a $234,025 loan amount and a 30-year fixed term. The historical interest rate was 6.375%, with a reported 7.185% APR.
A refinance should be evaluated against the existing loan, total costs and the homeowner’s plans. This case does not claim a payment reduction, cash-out amount or break-even period because those comparisons were not supplied. Use our refinance guide and refinance closing-cost guide to frame that discussion.
What to Review in Your Own Scenario
- Credit: Review the full report and loan options rather than assuming one score determines approval.
- Monthly obligations: Confirm the debts and qualifying income used for DTI, then compare the payment with your household budget.
- Cash and equity: Review property value, equity, closing costs and the comparison with your existing loan.
- Complete terms: Compare interest rate, APR, term and total costs using the Loan Estimate and Closing Disclosure.
★★★★★ · Google review
The Borrower’s Experience With Lyndi
“Working with Lyndi is always a pleasure. She has always been professional”
Borrower name omitted on this page. Read the original review on Google.
Excerpt from a public five-star review, verified October 12, 2026. The linked Google source displays the reviewer’s public profile. Reviews describe individual experiences and do not guarantee loan approval, terms or timing.
Louisiana Mortgage Loan Officer
This Closing Was Handled by Lyndi Gajan
Louisiana borrowers can work directly with Lyndi Gajan to review loan options, credit, qualifying debt payments, cash needed to close and next steps.
Lyndi Gajan NMLS ID 88249. 360 Mortgage Inc. NMLS ID 80777.
Addis Conventional Case Study FAQs
Can a homeowner refinance with a credit score below 680?
This borrower closed a conventional refinance with a 668 credit score. Another borrower’s options will depend on the complete credit profile, income, debts, equity and lender requirements.
Does this case mean conventional loans allow 50.99% DTI?
No. The case reports the DTI recorded for this individual closing. Program, underwriting and lender limits vary; this is not a general eligibility threshold.
Did this refinance lower the payment?
The available closing details do not include the prior loan or a payment comparison. No monthly savings or break-even claim is made.
Have a Similar Refinance Situation?
Talk with Lyndi about your credit, income, debts, property and existing mortgage and equity. A personal review can help you understand the options and next steps for your own file.
Talk With LyndiThis case study omits borrower names and loan numbers and describes one historical transaction for educational purposes. It is not a current rate quote, commitment to lend or guarantee of approval, rates, closing costs or results. Eligibility depends on the full borrower profile, property, program rules, lender requirements and underwriting review. 360 Mortgage Inc. NMLS ID 80777.