DSCR Loans in Waco, TX for Rental Property Investors
Compare supported rent, the full housing payment, and a realistic operating budget before financing a Waco rental.
Discuss your Waco scenario with Lyndi Calculate DSCRQuick answer: A Waco DSCR loan is business-purpose financing for an eligible rental property, with qualification centered on supported property income and lender guidelines. Compare the rental calculation with a full expense budget, and confirm the property use and lending channel before applying.
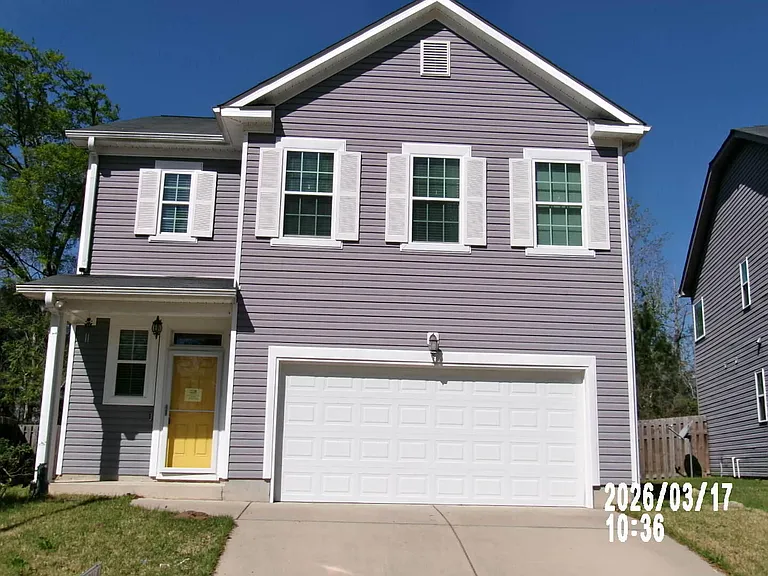
Real closing example — Georgia
No Personal Income Needed for This Rental Purchase
This example is from Grovetown, Georgia, not Waco. See how an investor used the property’s estimated $1,826 monthly rent to qualify for an $184,000 DSCR loan at 7.49% with no prepayment penalty—and how the deal pencils to approximately $205.83 monthly cash flow before other operating expenses.
View the Georgia DSCR purchase case studyHow a Waco DSCR loan works
A debt service coverage ratio loan evaluates an investment property’s supported rental income against its required housing payment. For many one-to-four-unit rental programs, that means monthly qualifying rent divided by principal, interest, taxes, insurance, and association dues when applicable. The lender’s actual method controls: commercial multifamily underwriting may instead use net operating income and annual debt service. These calculations should not be mixed together.
For Waco investors, the practical advantage is that a suitable business-purpose program may rely on the property’s income instead of qualifying through employment income and a conventional personal debt-to-income calculation. That does not eliminate credit, asset, appraisal, title, insurance, entity, or property review. A promising rent estimate is the beginning of a loan discussion, not a commitment to lend. Start with our DSCR loan explanation and requirements guide.
Waco is a metro market, not one uniform rental neighborhood
The Waco metropolitan area had an estimated 308,807 residents in July 2025, according to Census data published through the Federal Reserve Bank of St. Louis. That is a metropolitan estimate, not Waco’s city-limit population. Investors should still build a property-specific rental analysis rather than treating a metro population figure as proof of demand or profitability.
Baylor University’s main campus is in Waco near Interstate 35 and the Brazos River. That creates a useful location reference for evaluating a property, but proximity alone does not establish achievable rent. Compare actual lease terms, property condition, parking, bedroom layouts, and competing listings. A house marketed for an academic-year rental may have a different turnover pattern from a year-round single-family rental. Those are underwriting questions to investigate, not assumptions to copy into every Waco deal.
Compare locations by the address and intended rental use. Check access to work or campus, traffic at relevant hours, maintenance logistics, insurance quotes, and the pool of comparable rentals. A lower purchase price can be offset by deferred maintenance or weaker rent support. A higher-priced property can also struggle if the proposed payment outruns sustainable rent.
An illustrative purchase scenario: qualification is not cash flow
Consider a hypothetical Waco rental with supported monthly rent of $2,250 and a proposed full housing payment of $1,800. The simplified residential DSCR is 1.25: $2,250 divided by $1,800. These figures are an illustration, not a Waco rent estimate, interest-rate offer, or actual borrower approval.
The $450 difference is not automatically spendable profit. If the owner budgets $400 a month for vacancy, maintenance, capital replacements, and management, only $50 remains in this simplified illustration. An investor who looks only at the qualifying ratio can miss how thin the operating margin is. The lender’s DSCR calculation and the owner’s cash-flow model answer related but different questions.
Now reduce rent to $2,000 and raise the housing payment to $1,900. DSCR falls to about 1.05. Keeping the same $400 operating allowance produces an estimated $300 monthly deficit. This is why insurance, tax assumptions, reserves, and supported rent deserve attention before an investor chooses leverage. Use the DSCR calculator for the ratio, then review Blue Castle’s rental-deal analysis guide for the broader expense model.
Taxes and insurance can change the Waco loan calculation
Do not carry a seller’s tax bill into your rental budget without checking its assumptions. Texas residence-homestead relief is tied to qualification as a principal residence. An investment-property analysis should confirm the taxable value and exemptions applicable to the buyer’s actual use with the appraisal district. A seller’s exemption may make the historical bill a poor forecast for an investor.
Request an insurance quote that accurately describes rental occupancy, ownership, property condition, and intended use. Review the deductible and any separate flood coverage needed for the specific address. An inexpensive premium can still leave a large deductible exposure. A preliminary loan estimate should be updated when real taxes, insurance, and association dues become available.
Also separate financing reserves from operating reserves. Funds required by a lender do not necessarily provide enough protection against a roof replacement, a long vacancy, or an unexpected repair. Build a property budget that can tolerate ordinary ownership costs after closing instead of using every available dollar for the down payment.
Long-term leases, academic calendars, and short-term rentals
For a long-term Waco rental, review the existing lease, concessions, expiration date, deposits, and whether the current rent is supportable at renewal. Ask how the lender treats an occupied property versus a vacant purchase and what appraisal rent documentation is needed. A listing’s advertised rent and a signed lease are different kinds of evidence.
For a rental near Baylor, review the leasing calendar and whether you are underwriting a whole-home lease or separate bedroom arrangements. Confirm the lender accepts the actual structure, rather than assuming a student-oriented operating plan fits every standard rental program. Budget for turnover, cleaning, utilities if owner-paid, and a possible gap between lease cycles.
For short-term rentals inside Waco, the city requires an operating license and may require a special permit depending on the use and zoning. Confirm eligibility for the exact address and ownership change before relying on vacation-rental income. A seller’s existing operation is not proof that a buyer can continue the same use. Local approval, association restrictions, and lender acceptance are separate checks. Read the city’s current rules directly and compare short-term rental financing with long-term rental financing.
Purchase versus refinance: build the right file
A purchase review should establish the contract price, supported rent, available funds, inspection findings, and realistic closing timeline. Explain any immediate repairs and whether the property will be ready for its intended rental use when the loan closes. Do not assume permanent DSCR financing is also a construction or rehabilitation loan.
A refinance review starts with current ownership, the existing mortgage, recent improvements, current leases, and the intended use of any proceeds. Value, seasoning, available equity, loan-to-value limits, and the new payment can affect the result. If a proposed cash-out structure leaves little room for repairs or vacancies, compare a smaller loan amount before focusing on maximum proceeds.
This page concerns non-owner-occupied, business-purpose rental financing. A primary residence or Texas homestead is a different transaction and must not be represented as a DSCR investment loan merely because the borrower wants easier income documentation. Review the property’s actual use and transaction structure before selecting a lending channel.
LLC ownership and documentation
Some rental investors prefer an LLC; others hold a property personally. The accepted borrower structure depends on the lender and loan program. An LLC does not create rent support or guarantee approval. Read our LLC borrower guide before committing to an entity structure for the purchase.
If an LLC will borrow, prepare its formation documents, operating agreement when required, ownership information, and evidence of signing authority. Confirm how funds will move to closing and whether guarantees are required. The deed, insurance policy, lender documents, and entity name should be coordinated before closing. Ask your legal and tax advisers about ownership decisions; loan eligibility alone is not a complete entity strategy.
For out-of-area investors, include a realistic operating plan. Identify who will handle inspections, repairs, lease-up, and tenant communication. Our ecosystem resources can support analysis, but Blue Castle’s Kansas City-area leasing service should not be assumed to operate in Waco.
Prepare a Waco scenario for review
Send the property address, purchase price or estimated value, requested loan amount, proposed rental use, supported rent, estimated taxes and insurance, association dues, and available funds. Include whether you will borrow personally or through an LLC and whether the property is occupied, vacant, or being renovated.
If the file has a complication, explain it early. A short-term rental plan, unusual lease, recent ownership transfer, deferred maintenance, or thin reserves is easier to discuss before an appraisal or other expense is ordered. Compare the requested loan with a more conservative alternative so the conversation can focus on a durable investment rather than only reaching a threshold.
360 Mortgage can review the scenario and identify the appropriate next step subject to state, lender, property, and transaction eligibility. No page, calculator result, or preliminary discussion guarantees approval, a rate, or a closing date. Return to the Texas DSCR hub, compare Austin and Dallas, or explore the main DSCR resource hub.
DSCR and Investor Loan Guidance
Talk Through DSCR Loan Options With Lyndi Gajan
Real estate investors can work with Lyndi Gajan to talk through DSCR loan questions, rental income scenarios, refinance options, and investor documentation before choosing a loan path.
Lyndi Gajan NMLS ID 88249. 360 Mortgage Inc. NMLS ID 80777. Loan availability, licensing, and guidelines vary by state, property, and loan purpose.
Request your Waco investor financing review
Share the property address, rental plan, estimated rent and requested loan amount. Lyndi can review the scenario and discuss the next step.
Frequently asked questions about Waco DSCR loans
Can I use a DSCR loan for a Waco rental held in an LLC?
Some programs accept LLC borrowers, subject to entity documentation, signing authority, guarantees, and lender guidelines. An LLC does not eliminate credit, asset, appraisal, or rental-income review.
How is DSCR calculated for a Waco single-family rental?
Many residential investment programs divide supported monthly rent by principal, interest, taxes, insurance, and applicable association dues. Confirm the lender’s method; this ratio is not the same as the owner’s net cash flow.
Can short-term rental income qualify a Waco property?
Some lenders consider eligible short-term rental income. The investor must separately verify local licensing, zoning, association rules, and the lender’s required income documentation. Approval of one does not establish the others.
Should I use the property tax bill from the seller in my estimate?
Use it as a starting reference, then confirm taxes for your ownership and rental use. A seller’s principal-residence exemption may make the historical bill an unsuitable forecast.
Does a 1.25 DSCR guarantee positive cash flow?
No. A qualifying ratio may exclude vacancy, management, maintenance, and capital replacements from its payment denominator. Model those operating costs separately.
What information should I send for a Waco DSCR review?
Provide the address, rental use, price or value, loan request, supported rent, taxes, insurance, association dues, funds available, ownership structure, and current occupancy or repair status.
Local sources and review notes
Local facts checked October 8, 2026. Population is the July 2025 metro estimate; examples are illustrative and are not advertised rent or loan terms.
Comparing Central Texas investment markets? Our Killeen–Temple DSCR guide covers rentals near Fort Hood and Temple medical facilities, along with turnover and cash-flow planning.
Comparing university-area rentals beyond Waco? Review student lease timing and annual cash-flow planning in our College Station–Bryan DSCR guide.