360 Mortgage Real Closing Scenario
Georgia DSCR Purchase Case Study: No Personal Income Needed
A Grovetown rental-property purchase qualified using the subject property’s estimated $1,826 monthly rent—not the investor’s personal employment income.
Discuss a DSCR Loan With Lyndi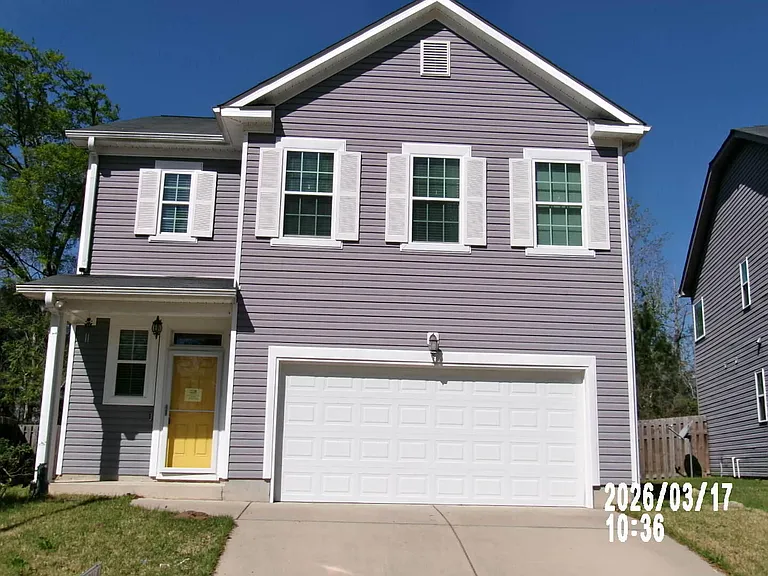
Closed-loan snapshot
This anonymized Georgia DSCR loan financed an $184,000 purchase loan on a $230,000 Grovetown investment property. Qualification centered on the property’s estimated rental income rather than the investor’s personal employment income.
Loan Snapshot
DSCR rental-property purchase
$230,000
$184,000
80%
7.49%
30-year fixed
None
$1,826/month
$205.83*
4.66%*
23.93%*
Historical terms from one closed transaction, not a current rate quote. *Illustrative cash flow and return use the assumptions and limitations explained below.
The Standout Feature: No Personal Income Used for Qualification
This investor did not need to qualify using W-2 wages, tax-return income, or another personal-income calculation. The DSCR structure evaluated the subject property’s supported rental income against its housing expense.
That distinction can make DSCR financing useful for self-employed investors, borrowers with complex tax returns, and rental-property owners whose personal income documentation does not fit traditional conventional underwriting. Credit, reserves, property eligibility, appraisal, rent support, entity structure, and lender guidelines can still apply.
Estimated Monthly Cash Flow
The estimated monthly rent was $1,826. The Closing Disclosure shows principal and interest of $1,285.29 and monthly escrow of $298.21. It also identifies annual non-escrowed HOA costs of $440.04, equal to approximately $36.67 per month.
| Estimated monthly rent | $1,826.00 |
|---|---|
| Principal and interest | -$1,285.29 |
| Escrowed taxes and insurance | -$298.21 |
| Monthly HOA allocation | -$36.67 |
| Estimated monthly cash flow | $205.83 |
This is a simplified cash-flow illustration before vacancy, repairs, maintenance, capital expenditures, property management, utilities, leasing costs, and other operating expenses. It should not be treated as formal net operating income.
Cash-on-Cash Return Calculation
Using the CD’s stated $52,972.22 cash to close, the estimated $205.83 monthly cash flow produces $2,469.96 of annual cash flow:
$205.83 × 12 = $2,469.96 annual cash flow
$2,469.96 ÷ $52,972.22 = 4.66% estimated cash-on-cash return
For a more conservative all-in view, the CD also shows a $1,000 deposit and $635 in closing costs paid before closing. Adding those amounts to cash to close produces $54,607.22 of total documented borrower funds and an estimated 4.52% cash-on-cash return.
Neither calculation assumes appreciation, principal paydown, tax benefits, rent growth, or future refinancing. Actual performance depends on collected rent and the property’s full operating costs.
Projected First-Year Total Return
Cash flow is only one part of a rental property’s potential economic return. Using a 3% annual appreciation assumption, the scheduled first-year principal reduction on this 30-year fixed loan, and a conservative illustrative depreciation tax benefit, the projected first-year return is:
| Estimated annual cash flow | $2,469.96 |
|---|---|
| Projected appreciation at 3% | $6,900.00 |
| Scheduled first-year principal paydown | $1,699.43 |
| Illustrative depreciation tax savings | $1,605.82 |
| Projected first-year economic benefit | $12,675.21 |
$12,675.21 ÷ $52,972.22 cash to close = 23.93% projected first-year total ROI
Using the more conservative $54,607.22 total documented borrower funds produces a projected 23.21% return.
Assumptions Behind the Projection
- Appreciation: 3% of the $230,000 purchase price, or $6,900. Appreciation is not guaranteed and is not cash unless realized through a sale or refinance.
- Mortgage paydown: Approximately $1,699.43 of principal during the first 12 scheduled payments, calculated from the $184,000 balance, 7.49% rate, 30-year term, and $1,285.29 principal-and-interest payment.
- Depreciation: An illustrative 80% building allocation ($184,000) depreciated over 27.5 years produces about $6,690.91 of annual depreciation.
- Tax savings: Applying an assumed 24% federal marginal tax rate to that depreciation produces approximately $1,605.82 of potential tax savings.
The tax illustration excludes land, cost-segregation adjustments, closing-cost basis adjustments, state taxes, depreciation recapture, passive-activity limitations, and the investor’s individual tax circumstances. Depreciation can reduce taxable income without increasing property cash flow, and some investors may not be able to use the full deduction currently. Consult a qualified tax professional.
What the Rent Says About Debt Coverage
Dividing the $1,826 estimated rent by the $1,620.17 combined monthly principal, interest, escrow, and HOA expense produces an illustrative coverage ratio of approximately 1.13x. In simple terms, the estimated rent was about 13% higher than those scheduled housing expenses.
This is an educational calculation from the supplied rent estimate and final CD—not a representation of the lender’s official underwriting ratio. DSCR formulas, qualifying rents, expense treatment, and minimum ratios vary among lenders.
Why No Prepayment Penalty Matters
The Closing Disclosure shows no prepayment penalty. That gives the investor more flexibility to sell, refinance, or pay down the loan without the contractual prepayment charge found in many DSCR programs.
No-prepayment-penalty options can carry different pricing than loans with a penalty. Investors should compare rate, points, lender credits, expected hold period, and exit strategy rather than evaluating the interest rate alone.
What Georgia Investors Can Learn From This Closing
- Personal employment income may not be required. This transaction relied on the investment property’s rent support rather than a traditional personal-income calculation.
- The property supported positive scheduled cash flow. Estimated rent exceeded principal, interest, escrow, and HOA by approximately $205.83 per month before other operating expenses.
- Cash-on-cash return depends on the denominator. Using cash to close produces 4.66%; including the prior deposit and paid-before-closing costs produces 4.52%.
- No prepayment penalty improves flexibility. The investor was not locked into a multi-year penalty period.
- Rate is only one part of the structure. The 7.49% fixed rate was paired with 80% financing, no mortgage insurance, and no prepayment penalty.
Georgia DSCR Purchase Case Study: Key Numbers
| Property area | Grovetown / Augusta, Georgia |
|---|---|
| Purchase price | $230,000 |
| Loan amount | $184,000 |
| Rate / term | 7.49% / 30-year fixed |
| Prepayment penalty | None |
| Estimated rent | $1,826/month |
| Scheduled housing expense | $1,620.17/month including HOA |
| Estimated monthly cash flow | $205.83 before other operating expenses |
| Cash to close | $52,972.22 |
| Estimated cash-on-cash return | 4.66% using cash to close |
Compare Other Real Closing Scenarios
See how a Louisiana investor used a DSCR cash-out refinance to access equity for renovations and furnishings. For a different loan type, review a VA IRRRL that closed in approximately 7-10 days.
★★★★★
“Always available to answer any questions.”
Verified 5-star client review · Customer name withheld for privacy · View the public review on Google
DSCR Loan Officer
This Georgia DSCR Purchase Was Handled by Lyndi Gajan
Investors can work directly with Lyndi Gajan to compare DSCR purchase and refinance options, rental-income qualification, leverage, reserves, and prepayment structures.
Lyndi Gajan NMLS ID 88249. 360 Mortgage Inc. NMLS ID 80777.
Georgia DSCR Purchase Case Study FAQs
Can a DSCR loan close without using personal income?
Yes, some DSCR programs qualify an investment-property loan using supported rental income and the property’s housing expense instead of traditional personal-income documentation. Other credit, reserve, property, appraisal, and lender requirements still apply.
How was the $205.83 monthly cash flow calculated?
The illustration subtracts $1,285.29 principal and interest, $298.21 escrow, and approximately $36.67 monthly HOA from the $1,826 estimated rent. It does not subtract vacancy, repairs, maintenance, management, utilities, leasing expenses, or capital expenditures.
How was the 4.66% cash-on-cash return calculated?
The $205.83 estimated monthly cash flow equals $2,469.96 annually. Dividing that by the CD’s $52,972.22 cash to close produces approximately 4.66%.
Did this DSCR loan have a prepayment penalty?
No. The final Closing Disclosure states that the loan did not have a prepayment penalty.
Could a DSCR Loan Fit Your Georgia Rental Purchase?
360 Mortgage can compare rent support, property expenses, leverage, reserves, pricing, and prepayment options for a Georgia investment-property purchase or refinance.
Talk With LyndiThis anonymized case study is for educational purposes and describes one historical transaction. It is not a commitment to lend, a current rate quote, tax advice, investment advice, or a guarantee of approval, rent, cash flow, return, or future performance. Rates, fees, DSCR calculations, qualifying rents, reserves, prepayment structures, property eligibility, loan-to-value limits, and underwriting requirements vary by lender and are subject to change. Cash-flow illustrations exclude vacancy and other operating expenses identified above. All loans are subject to lender review and approval. 360 Mortgage Inc. NMLS ID 80777.